Financial due diligence
Know what you are buying before you sign.
Quality of earnings and financial due diligence from Chartered Professional Accountants, for buyers and sellers of private companies in Canada and the United States.
Most sellers present adjusted EBITDA. Almost none of them present it the way a buyer would.
The gap between those two numbers is the deal. It is also where the purchase price was set, which means it is where the money is. A multiple applied to an EBITDA figure that does not survive testing is not a valuation. It is an estimate dressed up as one.
Our job is to find out which parts of that number hold.
What that gap usually is
Owner compensation that has to be normalized. Personal expenses inside operating costs. One-time items that happen every year. Capital expenditure expensed rather than capitalized.
Every adjustment is quantified and sourced, so you can defend it to a lender or an investment committee.
The record
Deals engaged and transactions completed are counted separately.
What we test
We start from management’s proposed adjustments and test each one against supporting documentation. Then we look for the adjustments nobody proposed. The ones we find most often:
Earnings adjustments
- Owner and officer salary that has to be normalized to market, particularly when the owner is leaving and the buyer will have to replace them
- Family members on payroll above market rates
- Personal expenses running through the company. Vehicles, travel, meals
Presentation and timing
- One-time items presented as recurring, and recurring items presented as one-time
- Capital expenditure expensed rather than capitalized
- Gains and losses on asset disposals sitting inside operating income
Balance sheet
- Deferred revenue, which in smaller companies is often not on the balance sheet at all
- Bad debt estimates that have not been revisited in years
- Cut-off errors around period end
We reconcile the bank statements to the books, receipts and disbursements separately, and we tell you the variance. If the books cannot be tied to cash, everything built on top of them is a guess, and that is worth knowing in week one rather than after close.
We present three periods: the two prior fiscal years and the trailing twelve months. One year of good numbers is not a trend.
Where buyers lose money after signing
The working capital peg is the most commonly underestimated line in a private company deal.
We calculate the normalized level of working capital the business actually needs to keep operating after close, on a cash-free and debt-free basis. We look at days sales outstanding, days payable outstanding, and inventory days to understand the cash conversion cycle, and we test the peg against the trailing twelve months, the last ninety days, and the two prior fiscal years, because the right benchmark depends on the business and not on convention.
We also list the debt and debt-like items that reduce what you are really paying for. Accrued bonuses. Deferred revenue. Off balance sheet leases. Contingent liabilities.
Getting the peg wrong by a few hundred thousand dollars is routine, and it comes straight out of the buyer’s pocket at close.
Debt and debt-like items we list
Accrued bonuses. Deferred revenue. Off balance sheet leases. Contingent liabilities.
Each one reduces what you are really paying for, and each belongs in the negotiation before signing rather than after.
Already have an LOI in hand?
Send it over and we will tell you whether the purchase price looks defensible on the information available, and where we would expect diligence to find problems.
What you receive
A written report you can hand to your lender, your board, or your investment committee.
Executive summary
A plain list of what we found and what each finding means for the price. This is the section your investment committee will read.
Quality of earnings
Every adjustment quantified and sourced, across the two prior fiscal years and the trailing twelve months.
Proof of cash
Bank statements reconciled to the books, with receipts and disbursements tested separately rather than netted.
Net working capital peg
The normalized level the business needs to keep operating after close, calculated cash-free and debt-free.
The report opens with a notice to readers stating what it is and what it is not. A quality of earnings engagement is not an audit and provides no assurance opinion. It is investigative work on the numbers, and the report says so on the first page.
Who does the work
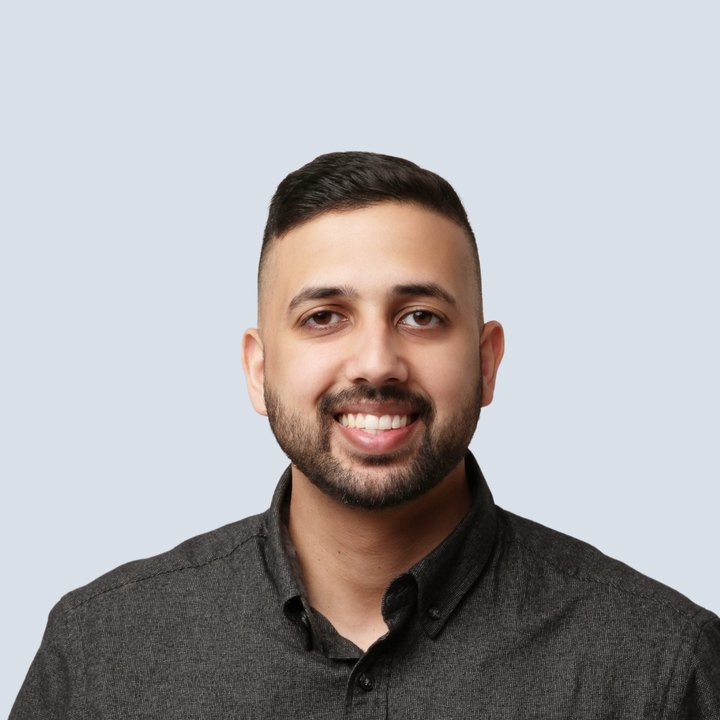
Avnit Sekhon, CPA
Director, Transaction Advisory
Leads every quality of earnings engagement.
The transaction advisory team sits inside Treewalk, a firm of Chartered Professional Accountants with more than 40 CPAs and more than 75 staff. That matters during a deal because diligence questions rarely stay inside diligence. Tax structuring, post close accounting, and controllership are down the hall rather than out for quote.
You work directly with the people doing the analysis, not through an account manager who relays questions.
Common questions
Do you work with buyers or sellers?
Both, on different engagements. Buy-side work is financial due diligence and quality of earnings for an acquirer. Sell-side work is preparing an owner for sale, which means running the same analysis on their own business first so the problems are found and fixed before a buyer’s advisor finds them. We do not act for both sides of the same transaction.
What size of transaction do you work on?
Owner-managed and lower middle market private companies, in Canada and the United States. If your deal is materially larger or smaller than that, tell us anyway and we will say honestly whether we are the right firm for it.
What happens after I send the LOI?
Avnit reads it, usually the same day. You get back a view on whether the purchase price looks defensible on the information available, and where we would expect diligence to find problems. If we think you do not need a full quality of earnings engagement, we will tell you that. If we do, you get a scope and a timeline before any fee conversation.
Is what I send you confidential?
Yes. Send the letter of intent and anything supporting it straight to Avnit by email. It stays inside the firm’s systems and is seen only by the people working on your file. We are Chartered Professional Accountants, and confidentiality under the CPA Code is a professional obligation rather than a policy. It applies whether or not you engage us, and it does not expire when the deal does.
What is a quality of earnings report?
The short answer is that it tests whether reported earnings reflect what the business actually earns on a sustainable basis, and documents every adjustment so the number can be defended. The longer answer, including what is inside the report and how it differs from an audit, is on the quality of earnings page.
Send us your LOI. We will review the purchase price.
A buyer with a signed letter of intent has already agreed a number. This tells you whether that number survives contact with the accounts, before diligence starts and while the other side is still cooperative.
- A view on whether the multiple looks defensible on the information available
- Where we would expect diligence to find problems
- An honest answer if you do not need a full engagement
Avnit will email you back. Reply to that message with the letter of intent attached.
No cost. One business day.